BLOG

To file or not to file a gift tax return, that is the question
If you made gifts last year you may be wondering if you need to file a gift tax return. The short answer: There are many situations when it’s necessary (or desirable) to file Form 709 — “United States Gift (and Generation-Skipping Transfer) Tax Return” — even if you’re not liable for any gift tax. Let’s take a closer look at the reasons why.
What gifts are considered nontaxable?
The federal gift tax regime begins with the assumption that all transfers of property by gifts (including below-market sales or loans) are taxable. It then sets forth several exceptions. Nontaxable transfers that need not be reported on Form 709 include:
Gifts of present interests within the annual exclusion amount ($17,000 per donee in 2023, up from $16,000 in 2022),
Direct payments of qualifying medical or educational expenses on behalf of an individual,
Gifts to political organizations and certain tax-exempt organizations,
Deductible charitable gifts,
Gifts to one’s U.S.-citizen spouse, either outright or to a trust that meets certain requirements, and
Gifts to one’s noncitizen spouse within a special annual exclusion amount ($175,000 in 2023, up from $164,000 in 2022).
If all your gifts for the year fall into these categories, no gift tax return is required. But gifts that don’t meet these requirements are generally considered taxable — and must be reported on Form 709 — even if they’re shielded from tax by the federal gift and estate tax exemption ($12.92 million in 2023, up from $12.06 million in 2022).
Are there tax traps to be aware of?
If you make gifts during the year, consider whether you’re required to file Form 709. And watch out for these common traps:
Future interests. The $17,000 annual exclusion applies only to present interests, such as outright gifts. Gifts of future interests, such as transfers to a trust for a donee’s benefit, aren’t covered, so you’re required to report them on Form 709 even if they’re less than $17,000 in 2023 ($16,000 in 2022).
Spousal gifts. As previously noted, gifts to a U.S.-citizen spouse need not be reported on Form 709. However, if you make a gift to a trust for your spouse’s benefit, the trust must 1) provide that your spouse is entitled to all the trust’s income for life, payable at least annually, 2) give your spouse a general power of appointment over its assets and 3) not be subject to any other person’s power of appointment. Otherwise, the gift must be reported.
Gift splitting. Spouses may elect to split a gift to a child or other donee, so that each spouse is deemed to have made one-half of the gift, even if one spouse wrote the check. This allows married couples to combine their annual exclusions and give up to $34,000 for 2023 (up from $32,000 for 2022) to each donee. To make the election, the donor spouse must file Form 709, and the other spouse must sign a consent or, in some cases, file a separate gift tax return. Keep in mind that, once you make this election, you and your spouse must split all gifts to third parties during the year.
The deadline to file Form 709 for 2022 is April 18. Please contact us if you’re unsure of whether you need to file a gift tax return this year.
© 2023

Provide your heirs the option of creating an inheritor’s trust
Even though it may not be top of mind when you’re developing or revising your estate plan, it’s important to consider how bequeathing assets to your family might affect them. Why? Because when your heirs receive their inheritance, it becomes part of their own taxable estates. Giving a loved one permission to create an inheritor’s trust can help avoid this outcome.
The trust in action
In a nutshell, an inheritor’s trust allows your loved one to receive the inheritance in trust, rather than as an outright gift or bequest. Thus, the assets are kept out of his or her own taxable estate. Having assets pass directly to a trust benefiting an heir not only protects the assets from being included in the heir’s taxable estate, but also shields them from other creditor claims, such as those arising from a lawsuit or a divorce.
Because the trust, rather than your family member, legally owns the inheritance, and because the trust isn’t funded by the heir, the inheritance is protected. The reason is because everything you gift or bequeath to the trust (including growth and income from the trust) is owned by the trust, and therefore can’t be treated as community property. An inheritor’s trust can’t replace a prenuptial or postnuptial agreement, but it can provide a significant level of asset protection in the event of divorce.
With an inheritor’s trust, your heir can also realize wealth building opportunities. If you fund an inheritor’s trust before you die, your loved one can use a portion of the money to, for example, start a new business. A prefunded inheritor’s trust can also own the general partnership interest in a limited partnership or the voting interest in a limited liability company or corporation. If you decide to fund the trust now, your initial gift to the trust can be as little or as much as you like.
Talk to your heirs first
As you draft or revise your estate plan and consider who to pass your assets to, it’s a good idea to talk to family members first. Determine if they would accept the bequests and then inform them of their option of creating an inheritor’s trust. Turn to us to help determine whether an inheritor’s trust is right for your situation.
© 2023

Reading the tea leaves: Potential tax legislation in the new Congress
The 2022 mid-term election has shifted the scales in Washington, D.C., with the Democrats no longer controlling both houses of Congress. While it remains to be seen if — and when — any tax-related legislation can muster the requisite bipartisan support, a review of certain provisions in existing laws may provide an indication of the many areas ripe for action in the next two years.
Retirement catch-ups at risk
The SECURE 2.0 Act, enacted at the tail end of 2022, reportedly includes a technical drafting error that jeopardizes the abilities of taxpayers to make catch-up contributions to their pre-tax or Roth retirement accounts. According to the American Association of Pension Professionals and Actuaries, under the existing statutory language, no participants will be able to make such contributions beginning in 2024.
The American Retirement Association has brought the issue to the attention of the U.S. Department of Treasury and the Joint Committee on Taxation (JCT), a nonpartisan congressional committee that assists with federal tax legislation. While the JCT has apparently acknowledged that the language does appear to be a drafting error, a timely correction is far from guaranteed.
Indeed, such “technical corrections” legislation once passed Congress routinely. However, it has proven more challenging in the political climate of the last decade or so. For example, it took three years for Congress to pass minor corrections to the first SECURE Act. And a glitch in the Tax Cuts and Jobs Act of 2017 (TCJA) affecting eligibility for bonus depreciation wasn’t corrected until the CARES Act became law in 2020.
Expiring tax provisions
Tax-related legislation often includes so-called “sunset” dates — the dates tax provisions will expire, absent congressional action. For example, the Consolidated Appropriations Act, enacted in 2021, boosted the allowable deduction for business meals from 50% to 100% for 2021 and 2022. In 2023, the deduction limit returned to 50%.
A JCT report released in January 2023 highlights numerous significant provisions that are scheduled to expire in coming years without congressional action to extend them. For example, several tax credits related to renewable and alternative energy will expire at the end of 2024.
But 2026 is the year when some of the most wide-reaching and particularly valuable provisions — many of them created or modified by the TCJA — are set to disappear. They include:
Lower individual tax rates,
Enhancements to the Child Tax Credit (CTC),
Health insurance premium tax credit enhancements,
The New Markets Tax Credit,
The employer credit for paid family and medical leave,
The Work Opportunity Tax Credit,
The increase in the exemption amount and phaseout threshold for the alternative minimum tax,
The increase in the standard deduction,
The suspension of the miscellaneous itemized deduction,
The suspension of the limit on itemized deductions,
The income exclusion for employer payments of student loans,
The suspension of the deduction for personal exemptions,
The limit on the deduction for qualified residence interest,
The suspension of the deduction for home equity interest,
The limit on the deduction for state and local taxes,
The qualified business income deduction,
The deduction percentages for foreign-derived intangible income and global intangible low-taxed income,
Empowerment zone tax incentives, and
The increase in the federal gift and estate tax exemption.
At the end of 2026, bonus depreciation also is slated for elimination. In fact, the allowable deduction already has dropped from 100% to 80% of the cost of qualified assets in 2023. The limit will drop by 20% each year until vanishing in 2027.
Expired tax provisions
Several notable provisions expired or changed at the end of 2021, despite chatter in Washington about the possibility of extensions. For example, as of 2022, taxpayers can no longer deduct Section 174 research and experimentation expenses, including software development costs, in the year incurred. Rather, they must amortize these expenses over five years (or 15 years if incurred outside of the United States). In addition, the calculation of adjusted taxable income for purposes of the limit on the business interest deduction has changed, potentially reducing the allowable deduction for some taxpayers.
Individuals also saw the end of several tax provisions at the end of 2021, including the:
CTC expansions created by the American Rescue Plan for some taxpayers,
Expanded child and dependent care credit,
Increased income exclusion for employer-provided dependent care assistance,
Treatment of mortgage insurance premiums as deductible mortgage interest,
Charitable contribution deduction for non-itemizers, and
Increased percentage limits for charitable contributions of cash.
It’s possible that some of these could be included in any “extender” legislation Congress might consider this year or next.
The FairTax Act
Unlikely to see much progress, however, is the proposed FairTax Act. Although it has the support of a group of U.S. House Republicans, GOP House Speaker Kevin McCarthy has stated that he doesn’t support the legislation.
The bill would eliminate most federal taxes — including individual and corporate income, capital gains, payroll and estate taxes — as well as the IRS. It would replace the taxes with a 23% federal sales tax on goods and services, which couldn’t be offset by deductions or tax credits. The plan has been around for two decades and has yet to garner a floor vote, an indicator of its odds this time around — especially with Democrats in control of the U.S. Senate.
Ear to the ground
Congress may not feel a sense of urgency to address tax provisions that aren’t set to expire for three years, but the catch-up contribution error would have substantial repercussions for many taxpayers in less than a year. We’ll let you know if lawmakers take action on this or any other important tax matters that could affect you.
© 2023
Look to a SWOT analysis to make better HR decisions
Many business owners spend most of their time developing strategic plans, overseeing day-to-day operations and, of course, putting out fires. Yet an underlying source of both opportunity and trouble can be human resources (HR).
Think about it: The performance of your HR department determines who works for you, how well employees are supported, and to what extent the business complies with laws and regulations pertaining to employment and benefits.
One way to ensure that your strategic HR decisions are likely to yield positive, cost-effective results is to apply a strengths, weaknesses, opportunities and threats (SWOT) analysis.
Strengths and weaknesses
When used for general strategic planning, a SWOT analysis typically begins by identifying strengths — usually competitive advantages or core competencies that generate value, such as a strong sales force or exceptional quality of products or services.
Next, you pinpoint weaknesses. These are factors that limit business performance, which are often revealed in comparison with competitors. General examples include a negative brand image because of a recent controversy or an inferior reputation for customer service.
When applying a SWOT analysis to HR, think about that department’s core competencies. These include filling open positions, administering benefits, and supporting employees who need help or are in crisis. What are its strengths? What are its weaknesses?
You can use various HR metrics to put a finer point on these relatively broad questions. For example, calculate “time to hire” to determine how long it’s taking to fill open positions and “early turnover” to see how many new hires you’re losing in the first year of employment.
External conditions
The next step in a typical SWOT analysis is identifying opportunities and threats. Opportunities are favorable external conditions that could generate a worthwhile return if the business acts on them. Threats are external factors that could inhibit performance or undermine strategic objectives.
When differentiating strengths from opportunities, or weaknesses from threats, ask yourself whether an issue would exist if your company didn’t. If the answer is yes, the issue is external and, therefore, an opportunity or threat. Examples include changes in hiring demographics or government regulations regarding benefits.
How to apply it
Let’s say you determine, by benchmarking yourself against similar businesses, that “time to hire” is a strength. This means that your HR staff is skilled at placing targeted, effectively worded ads; working well with recruiters; and interacting in a timely, efficient and positive manner with applicants.
In today’s environment, a strong hiring mechanism is undoubtedly a competitive advantage. If hiring and retention are weaknesses, however, you could be headed toward a crisis if you lose too many employees — particularly in today’s tight job market.
Opportunities and threats are important as well. For example, if your company seeks to strengthen employee retention through expanded benefits, you’ll need to anticipate the opportunities and challenges for your HR staff. You may need to invest in training and upskilling to make sure that they can effectively communicate with employees about the broader package and administer the specific benefits therein.
And there are likely external threats to consider. For example, an aggressive competitor may begin poaching your employees. Evolving tax regulations and compliance requirements for health and retirement benefits could catch your HR staff off-guard if they’re unaware of the changes.
Advisable and feasible
Sometimes business owners assume that HR will run itself while they dedicate themselves to growing the company. But the truth is that HR departments need to set strategic goals, just like the business does. A SWOT analysis can help ensure that these goals are advisable and feasible.
© 2023

Is your revocable trust fully funded?
A revocable trust — sometimes known as a “living trust” — can provide significant benefits. They include the ability to avoid probate of the assets the trust holds and facilitating management of your assets in the event you become incapacitated. To obtain these benefits, however, you must fund the trust — that is, transfer title of assets to the trust or designate the trust as the beneficiary of retirement accounts or insurance policies.
Inventory your assets
To the extent that a revocable trust isn’t funded — for example, if you acquire new assets but fail to transfer title to the trust or name it as the beneficiary — those assets may be subject to probate and will be beyond the trust’s control in the event you become incapacitated.
To avoid this result, periodically take inventory of your assets. This can better ensure that your trust is fully funded.
Max out FDIC insurance coverage
Another important reason to fund your trust is the ability to maximize FDIC insurance coverage. Generally, individuals enjoy FDIC insurance protection on bank deposits up to $250,000.
But with a properly structured revocable trust account, it’s possible to increase that protection to as much as $250,000 per beneficiary. So, for example, if your revocable trust names five beneficiaries, a bank account in the trust’s name is eligible for FDIC insurance coverage up to $250,000 per beneficiary, or $1.25 million ($2.5 million for jointly owned accounts).
Note that FDIC insurance is provided on a per-institution basis, so coverage can be multiplied by opening similarly structured accounts at several different banks. FDIC rules regarding revocable trust accounts are complex, especially when a trust has more than five beneficiaries, so talk to us to maximize insurance coverage of your bank deposits.
© 2023
Sailing a steady ship in today’s interesting economy
Business owners: If you’re having trouble reading the U.S. economy, you’re not alone. On the one hand, the January 2023 jobs report revealed that the unemployment rate had fallen to 3.4%, its lowest level in 54 years. And inflation, while still a concern, has moderated in most sectors — staving off fears of a recession in the immediate future.
And yet concern remains about whether the economy will grow or suddenly stall. And the Fed is expected to continue raising interest rates, meaning the battle against inflation is far from won. What can you do, strategically, to neither under- nor overreact to this “interesting” situation? Sail a steady ship.
Save a little, spend a little
In a faltering economy, business owners tend to want to curb spending. Conversely, during boom times, companies are more apt to spend money to seize opportunities. Right now, the best approach may be a little of both.
Enlist employees to help cut expenses that don’t foster your business’s long-term success. Communicate regularly with staff about the need to curb spending and celebrate those who come up with effective cost-control measures.
That said, now isn’t the time to stop investing in new assets, people or technologies if they’re essential to your operations or could sharpen your company’s competitive edge.
Prioritize expenditures
A good exercise to undertake at least annually, if not quarterly, is to make a list of all expenses over the course of a year and separate them into three categories: “must have,” “nice to have” and “don’t need.” Ask your leadership team for input on which expenses should fall under each category.
Another idea for small to midsize businesses: Have a “check-signing social” in which you gather department managers to discuss major cash outlays while you sign checks or otherwise remit payments. An event like this lets managers know that you’re aware of their spending while giving them a chance to explain their rationale for the spending.
Know your suppliers
In tough economic times, businesses must keep a close eye on the stability of suppliers. If a major vendor goes under, you could be left in the lurch.
You might not have to worry quite as much about insolvencies in today’s environment, but don’t let your guard down. Nurturing good relationships with suppliers is particularly vital with supply chain issues continuing to trouble many industries. Maintain strong communication. Every so often, you may want to conduct a supplier audit to collect key data points regarding each one’s performance.
Watch out for fraud
No matter what the state of the economy, dishonest employees and outside criminals may seize the opportunity to commit fraud. Cash and asset misappropriation, as well as outright theft, are among the most prevalent types of “traditional” fraud. Cybercrimes are also increasingly common today. Hackers can steal from you or shut down your operations from hundreds or thousands of miles away.
Reduce typical fraud risks by implementing a solid system of internal accounting controls, such as segregating duties and requiring a second signature on checks over a certain amount. Also, if you’re hiring, conduct thorough background checks within legal parameters. Finally, invest time and money in cybersecurity measures to protect your systems and data.
Good news, bad news
The good news is the U.S. economy has generally rebounded well from the many changes and challenges of the pandemic. The bad news is, no one is completely sure where we’re headed. Our firm can help you gather and analyze the right financial data to make strong strategic decisions.
© 2023

Joint ownership isn’t right for all estate plans
Generally speaking, owning property jointly benefits an estate plan. Indeed, joint ownership offers several advantages for surviving family members. However, there are exceptions and it’s not the solution for all estate planning problems.
2 types of joint ownership for spouses
As the name implies, joint ownership requires interests in property by more than one party. The type of joint ownership depends on the wording of the title to the property.
From a legal standpoint, there may be two main options for married couples:
Joint tenants with rights of survivorship (JTWROS). This is the most common form and often is used for a personal residence or other real estate. With JTWROS, one spouse’s share of the property can be sold without the other spouse’s consent. The property is subject to the reach of creditors of all owners.
Tenancy by the entirety (TBE). In this case, one spouse’s share of the property in some states can’t be sold without the other spouse joining in. But TBE offers more protection from creditors in noncommunity property states if only one spouse is liable for the debt. Currently, a TBE is available in slightly more than half the states.
Property may also be owned as a “tenancy in common.” With this form of ownership, each party has a separate transferable right to the property. Generally, this would apply to co-owners who aren’t married to each other, though in certain situations married couples may opt to be tenants in common.
Joint ownership plusses and minuses
The main estate planning attraction of joint ownership is that the property avoids probate. Probate is the process, based on prevailing state law, whereby a deceased person’s assets are legally transferred to the beneficiaries. Depending on the state, it may be time-consuming or costly — or both — as well as being intrusive. Jointly owned property, however, simply passes to the surviving owner.
Joint ownership is a convenient and inexpensive way to establish ownership rights. But the long-standing legal concept has its drawbacks, too. Some disadvantages of joint ownership relate to potential liability for federal gift and estate tax. Comparable rules may also apply on the state level.
For starters, if parties other than a married couple create joint ownership, it generally triggers a taxable gift, unless each one contributed property to obtain a share of the title. However, for a property interest in securities or a financial account, there’s no taxable gift until the other person actually makes a withdrawal.
Lessons to be learned
Joint ownership can be a valuable estate planning tool, especially because it avoids probate. However, this technique shouldn’t be considered a replacement for a will. We can help you coordinate joint ownership with other aspects of your estate plan.
© 2023
3 ways your business can uncover cost cuts
Every business wants to find them, but they sure don’t make it easy. We’re talking about cost cuts: clear and substantial ways to lower expenses, thereby strengthening cash flow and giving you a better shot at strong profitability.
Obvious places to slash costs — such as wages, benefits, and overhead — often aren’t a viable option because the very stability of your operation may depend on them. But there might be other ways to lower expenses if you dig deeply enough. Here are three ways to perhaps uncover some cost-cutting opportunities.
1. Study your suppliers
Many companies find that just a few of their suppliers account for most of their spending. By identifying these vendors and consolidating spending with them, you may be able to put yourself in a stronger position to negotiate volume discounts. Consolidating your supplier base also tends to streamline the administrative work associated with purchasing.
On a related note, how well do you know your suppliers? One way to ensure you’re working off an abundance of relevant information is to conduct a supplier audit. This is a formal process for collecting key data points regarding a supplier’s performance to manage quality control and ensure you’re getting an acceptable return on investment.
2. Go green
Given the already noticeable effects of climate change, operating an environmentally friendly company has become imperative. But going green can, under the right circumstances, save you money as well.
Refurbished computers or office furniture often can be found at substantial savings compared with their brand-new counterparts. If you no longer need equipment, computing devices, or office furniture, you may be able to sell them to a liquidator or dealer. You’ll not only bring in some money on the sales but also free yourself of the need to store and maintain the items.
In addition, look at your facilities. If you own the property on which you operate, research energy-efficient upgrades to the HVAC and lighting systems. Naturally, making such upgrades will cost you money initially, but you may be able to lower energy costs over the long term. What’s more, you might qualify for tax credits for installing certain items.
3. Explore outsourcing, tech upgrades
Many business owners try to cut costs by doing everything in-house — from accounting to payroll to HR. But if the staffing and expertise just aren’t there, these companies often suffer losses because of mistakes and mismanagement. Although you’ll obviously incur costs when outsourcing, the time and labor it saves you could end up being a net gain.
Carefully chosen and implemented technology upgrades can serve a similar purpose. Many products on the market today are so robust and fully featured, upgrading to them is almost comparable to outsourcing.
Again, you’ll need to spend money in the near term but, eventually, you could lower the cost of doing business. For example, the right customer relationship management system can help you generate sales leads and focus on your most profitable existing customers.
Snip, snip, snip
Lowering expenses is often difficult, but looking for ways to do it is an important activity to undertake regularly. This is particularly true now that inflation is a major factor in the economic landscape. Please contact us for help identifying and lowering your company’s most “cuttable” costs.
© 2023
Is now the time for your small business to launch a retirement plan?
Many small businesses start out as “lean enterprises,” with costs kept to a minimum to lower risks and maximize cash flow. But there comes a point in the evolution of many companies — particularly in a tight job market — when investing money in employee benefits becomes advisable, if not downright mandatory.
Is now the time for your small business to do so? More specifically, as you compete for top talent and look to retain valued employees, would launching a retirement plan help your case? Quite possibly, and the good news is the federal government is offering some intriguing incentives for eligible smaller companies ready to make the leap.
Late last year, the Consolidated Appropriations Act, 2023 was signed into law. Within this massive spending package lies the Setting Every Community Up for Retirement Enhancement 2.0 Act (SECURE 2.0). Its provisions bring three key improvements to the small employer pension plan start-up cost tax credit, beginning this year:
1. Full coverage for the smallest of small businesses. SECURE 2.0 makes the credit equal to the full amount of creditable plan start-up costs for employers with 50 or fewer employees, up to an annual cap. Previously only 50% of costs were allowed — this limit still applies to employers with 51 to 100 employees.
2. Glitch fixed for multiemployer plans. SECURE 2.0 retroactively fixes a technical glitch that prevented employers who joined multiemployer plans in existence for more than three years from claiming the small employer pension plan start-up cost credit. If your business joined a pre-existing multiemployer plan before this period, contact us about filing amended returns to claim the credit.
3. Enhancement of employer contributions. Perhaps the biggest change wrought by SECURE 2.0 is that certain employer contributions for a plan’s first five years now may qualify for the credit. The credit is increased by a percentage of employer contributions, up to a per-employee cap of $1,000, as follows:
100% in the plan’s first and second tax years,
75% in the third year,
50% in the fourth year, and
25% in the fifth year.
For employers with between 51 and 100 employees, the contribution portion of the credit is reduced by 2% times the number of employees above 50.
In addition, no employer contribution credit is allowed for contributions for employees who make more than $100,000 (adjusted for inflation after 2023). The credit for employer contributions is also unavailable for elective deferrals or contributions to defined benefit pension plans.
To be clear, though the name of the tax break is the small employer pension plan start-up cost credit, it also applies to qualified plans such as 401(k)s and SIMPLE IRAs, as well as to Simplified Employee Pensions. Our firm can help you determine whether now is indeed the right time for your small business to launch a retirement plan and, if so, which one.
© 2023

Deciding whether to make lifetime gifts or bequests at death can be a deceptively complex question
One of your primary estate planning goals may be to pass as much of your wealth to your family as possible. That means sheltering your estate from gift and estate taxes. One way to do so is to make gifts during your lifetime.
Current tax law may make that an enticing proposition, given the inflation-adjusted $12.92 million gift and estate tax exemption. However, making lifetime gifts isn’t right for everyone. Depending on your circumstances, there may be tax advantages to keeping assets in your estate and making bequests at death.
Tax consequences of gifts vs. bequests
The primary advantage of making lifetime gifts is that by removing assets from your estate, you shield future appreciation from estate tax. But there’s a tradeoff: The recipient receives a “carryover” tax basis — that is, he or she assumes your basis in the asset. If a gifted asset has a low basis relative to its fair market value (FMV), then a sale will trigger capital gains taxes on the difference.
An asset transferred at death, however, currently receives a “stepped-up basis” equal to its date-of-death FMV. That means the recipient can sell it with little or no capital gains tax liability. So, the question becomes, which strategy has the lower tax cost: transferring an asset by gift (now) or by bequest (later)? The answer depends on several factors, including the asset’s basis-to-FMV ratio, the likelihood that its value will continue appreciating, your current or potential future exposure to gift and estate taxes, and the recipient’s time horizon — that is, how long you expect the recipient to hold the asset after receiving it.
Estate tax law changes ahead
Determining the right time to transfer wealth can be difficult because so much depends on what happens to the gift and estate tax regime in the future. (Indeed, without further legislation from Congress, the base gift and estate tax exemption amount will return to an inflation-adjusted $5 million in 2026.) The good news is that it may be possible to reduce the impact of this uncertainty with carefully designed trusts.
Let’s say you believe the gift and estate tax exemption will be reduced dramatically in the near future. To take advantage of the current exemption, you transfer appreciated assets to an irrevocable trust, avoiding gift tax and shielding future appreciation from estate tax. Your beneficiaries receive a carryover basis in the assets, and they’ll be subject to capital gains taxes when they sell them.
Now suppose that, when you die, the exemption amount hasn’t dropped, but instead has stayed the same or increased. To hedge against this possibility, the trust gives the trustee certain powers that, if exercised, cause the assets to be included in your estate. Your beneficiaries will then enjoy a stepped-up basis and the higher exemption shields all or most of the assets’ appreciation from estate taxes.
Work with us to monitor legislative developments and adjust your estate plan accordingly. We can suggest strategies for building flexibility into your plan to soften the blow of future tax changes.
© 2023

A single parent’s estate plan should address specific circumstances
According to the Pew Research Center, nearly a quarter (23%) of U.S. children under the age of 18 live with one parent. This is more than three times the share (7%) of children from around the world who do so. If your household falls into this category, ensure your estate plan properly accounts for your children.
Choosing a guardian
In many respects, estate planning for single parents is similar to estate planning for families with two parents. Single parents want to provide for their children’s care and financial needs after they’re gone. But when only one parent is involved, certain aspects of an estate plan demand special attention.
One example is selecting an appropriate guardian. If the other parent is unavailable to take custody of your children if you become incapacitated or die suddenly, does your estate plan designate a suitable, willing guardian to care for them? Will the guardian need financial assistance to raise your kids and provide for their education? Depending on the situation, you might want to preserve your wealth in a trust until your children are grown.
Trust planning is one of the most effective ways to provide for your children. Trust assets are managed by one or more qualified, trusted individual or corporate trustees, and you specify when and under what circumstances the funds should be distributed to your kids. A trust is particularly important if you have minor children. Without one, your assets may come under the control of your former spouse or a court-appointed administrator.
Addressing incapacitation
As a single parent, it’s particularly important for your estate plan to include a living will, advance directive or health care power of attorney. These documents allow you to specify your health care preferences in the event you become incapacitated and to designate someone to make medical decisions on your behalf.
You should also have a revocable living trust or durable power of attorney that provides for the management of your finances in the event you’re unable to do so.
If you’ve recently become a single parent, contact us because it’s critical to review and, if necessary, revise your estate plan. We’d be pleased to help.
© 2023

Getting into data analytics without breaking the bank
Most business owners would probably agree that, in today’s world, data rules. But finding, organizing and deriving meaning from the terabytes upon terabytes of information out there isn’t easy.
How can your company harness the power of data without throwing dollars into the technological void? By investing in a formal initiative to incorporate data analytics into your decision making and strategic planning. However, as is so often the case, this is much easier said than done.
What is it?
Data analytics is the science of collecting and analyzing sets of data to develop useful insights, make connections between data points, and identify trends or patterns.
The process incorporates research, computer programming and statistical analysis to produce various types of data analytics — such as predictive, prescriptive, diagnostic and descriptive. The information used can come from both internal and external sources. Internal sources typically include a company’s financial statements, sales records and customer database. External data may be obtained from government websites, industry associations, publicly distributed surveys and social media.
What are the advantages?
There are several potential advantages of data analytics for businesses. When done right, it will shed light on what could help or hinder you in fulfilling strategic objectives and improving performance in a cost-efficient way. More specifically, data analytics can enable you to:
Evaluate the feasibility of an expensive ad campaign or product development idea,
Narrow down who your most potentially valuable customers are and how to reach them,
Decide whether to obtain outside financing and, if so, how much, and
Streamline operations and/or cut costs with a clear idea of what the positive outcomes will be.
Perhaps best of all, data analytics facilitates fact-based discussions and planning. This can head off emotionally based arguments and diminish the impact of “office politics” on whether the company should make a major move.
Will I need special software?
Generally, a business will need to invest in data analytics software to reap the advantages. If you decide to do so, it’s important not to put the cart before the horse. That is, you don’t want to run out and buy an expensive product and then figure out how to use it. Your company’s informational needs should dictate what you buy.
Today’s software can produce thousands of metrics, so you’re best off first determining which ones you want to track — now and down the road. You also need to ensure that the solution you buy comes with strong cybersecurity protections and complies with any applicable privacy and security regulations.
Additionally, you should determine how well a prospective data analytics solution would integrate with your other applications and data. If the software can’t access vital information, or employees have to input data manually, it will likely be a poor investment.
Is it right for you?
Properly used, and supported by the right software, data analytics can give your business a competitive edge. But it can be a costly endeavor that may call for an outside consultant to get you up and running. Contact us for help identifying which metrics you should target as well as forecasting the requisite costs — both upfront and ongoing — likely to be involved.
© 2023

Run the numbers before donating appreciated assets to charity
Are you charitably inclined? If so, you probably know that donations of long-term appreciated assets, such as stocks, have an advantage over cash donations. But in some cases, selling appreciated assets and donating the proceeds may be a better strategy.
That’s because adjusted gross income (AGI) limitations on charitable deductions are higher for cash donations. Plus, if the assets don’t qualify for long-term capital gain treatment, the deduction rules are different.
Tax treatments by type of gift
All things being equal, donating long-term appreciated assets directly to charity is preferable. Not only do you enjoy a charitable deduction equal to the assets’ fair market value on the date of the gift (assuming you itemize deductions on your return), you also avoid capital gains tax on their appreciation in value. If you were to sell the assets and donate the proceeds to charity, the resulting capital gains tax could reduce the tax benefits of your gift.
But all things aren’t equal. Donations of appreciated assets to public charities are generally limited to 30% of AGI, while cash donations are deductible up to 60% of AGI. In either case, excess deductions may be carried forward for up to five years.
Work the math
If you’re contemplating a donation of appreciated assets that’s greater than 30% of your AGI, crunch the numbers first. Then determine whether selling the assets, paying the capital gains tax and donating cash up to 60% of AGI will produce greater tax benefits in the year of the gift and over the following five tax years. The answer will depend on several factors, including the size of your gift, your AGI in the year of the gift, your projected AGI in the following five years and your ability to itemize deductions in each of those years.
Before making charitable donations, discuss your options with us. We can help you make charitable gifts at the lowest tax cost.
© 2023
Look forward to next year by revisiting your business plan
Businesses of all stripes are about to embark upon a new calendar year. Whether you’ve done a lot of strategic planning or just a little, a good way to double-check your objectives and expectations is to revisit your business plan.
Remember your business plan? If you created one recently, or keep yours updated, it might be fresh in your mind. But many business owners file theirs away and bust them out only when asked to by lenders or other interested parties.
Reviewing and revising your business plan can enable you and your leadership team to ensure everyone is on the same page strategically as you move forward into the new year.
6 traditional sections
Comprehensive business plans traditionally comprise six sections:
Executive summary,
Business description,
Industry and marketing analysis,
Management team description,
Implementation plan, and
Financials.
Business plans are a must for start-ups. And, as mentioned, they’re sometimes part of the commercial lending process. Yet business plans are often overlooked when leadership teams engage in strategic planning.
The best ones can be quite simple. In fact, long-winded business plans can wind up confusing everyone involved or simply go ignored. For a small business, the executive summary shouldn’t exceed one page, and the maximum number of pages of the entire plan should generally be fewer than 40.
Spotlight on financials
The executive summary is usually the first thing anyone looks at when reading a business plan, but it’s the last section you should write. Start with your company’s historic financial results, assuming it’s not a start-up. Then, identify key benchmarks that you want to achieve in the coming year — as well perhaps longer periods, such as three, five or even 10 years out.
Next, generate financial projections that support your strategic goals. For example, suppose your company has $10 million in sales in 2022 and expects to double that figure over a three-year period. How will you get from Point A ($10 million in 2023) to Point B ($20 million in 2025)?
Let’s say you and your leadership team decide to double sales by hiring four new salespeople and acquiring the assets of a bankrupt competitor. These strategic objectives will drive the projected income statement, balance sheet and cash flow statement included in your business plan.
Be particularly sure you’ve discussed how you’ll fund any cash shortfalls that take place as the company grows. Cash flow projections are critical for fruitful strategic planning, as well as for applying for a loan.
Blueprint for the future
One could say that integrating your strategic planning objectives into your business plan is a way to make your strategic plan “official.” By putting it in writing, and including the necessary financial documentation, you’ll have a blueprint of how to build the future of the business. Contact us for help.
© 2022

Addressing IP in an estate plan can be tricky
Over your lifetime, you may have accumulated a wide variety of tangible assets, including automobiles, works of art and property, that you’ve accounted for in your estate plan. But intangible assets can easily be overlooked.
Consider intellectual property (IP), such as patents and copyrights. These assets can have great value, so, if you have them, it’s important to properly address them in your estate plan.
Common forms of IP
IP generally falls into one of these categories: patents, copyrights, trademarks or trade secrets. Here we’ll focus on patents and copyrights, which are protected by federal law to promote scientific and creative endeavors by providing inventors and artists with exclusive rights to exploit the economic benefits of their work for a predetermined time.
Patents protect inventions, and the two most common are utility and design patents. A utility patent may be granted to someone who “invents or discovers any new and useful process, machine, manufacture, or composition of matter, or any new and useful improvement thereof.” A design patent is available for a “new, original and ornamental design for an article of manufacture.” To obtain patent protection, inventions must be novel, “nonobvious” and useful.
Utility patents protect an invention for 20 years from the patent application filing date. Design patents filed on or after May 13, 2015, last 15 years from the patent issue date. There’s a difference between the filing date and issue date. For utility patents, it takes at least a year and a half from date of filing to date of issue.
Copyrights protect the original expression of ideas that are fixed in a “tangible medium of expression.” These tangible mediums of expression typically take the form of written works, music, paintings and photographs.
Unlike patents, which must be approved by the U.S. Patent and Trademark Office, copyright protection kicks in as soon as a work is fixed in a tangible medium. For works created in 1978 and later, an author-owned copyright generally lasts for the author’s lifetime plus 70 years.
Estate planning for IP
For estate planning purposes, a key question is: What’s it worth? Valuing IP is a complex process. It’s best to obtain an appraisal from a professional with experience valuing IP. After you know the IP’s value, decide whether to transfer it to family members or charity through lifetime gifts or bequests after your death.
It’s important to plan the transaction carefully to ensure that your objectives are achieved. There’s a common misconception that, when you transfer ownership of the tangible medium on which IP is recorded, you also transfer the IP rights. But IP rights are separate from the work itself and are retained by the creator — even if the work is sold or given away.
Contact us to learn more on addressing IP in your estate plan.
© 2022

Should you consider a psychiatric advance directive?
Many people include health care powers of attorney or advance directives in their estate plans so they have some influence over critical medical decisions in the event they’re incapacitated and unable to make decisions themselves. A psychiatric advance directive (PAD) is less well known, but worth considering, especially if your family has a history of mental illness.
Health care directives
To cover all the health care bases, have two documents: an advance health care directive (sometimes referred to as a “living will”) and a health care power of attorney (HCPA). Some states allow you to combine the two in a single document.
An advance directive expresses your preferences for the use of life-sustaining medical procedures and specifies the situations in which these procedures should be used or withheld.
A document prepared in advance can’t account for every scenario or contingency. However, it’s wise to pair an advance directive with an HCPA. This allows you to authorize your spouse or other trusted representative to make medical decisions or consent to medical treatment on your behalf if you’re unable to do so.
Why a PAD?
Many states allow generic HCPAs and advance directives to address mental as well as physical health issues. But some states limit or prohibit mental health treatment decisions by general health care representatives. Around half of the states have PAD statutes, which authorize special advance directives to outline one’s wishes with respect to mental health care and appoint a representative to make decisions regarding that care.
PADs may address a variety of mental health care issues, including:
Preferred hospitals or other providers,
Treatment therapies and medications that may be administered,
Treatment therapies and medications that may not be administered, such as electroconvulsive therapy or experimental drugs,
A statement of general values, principles or preferences to follow in making mental health care decisions, and
Appointment of a representative authorized to make decisions and carry out your wishes with respect to mental health care in the event you’re incapacitated.
Although requirements vary from state to state, to be effective, a PAD must be signed by you and your chosen representative, and in some states by two witnesses. Be sure to discuss the terms of the PAD with your family, close friends, physician and any mental health care providers. And to be sure that the PAD is available when needed, give copies to all of the above persons, keep the original in a safe place and let your family know where to find it.
If you’re concerned about the possibility of mental illness and wish to have some say over your treatment in the event you’re incapacitated, contact us to learn more about a PAD.
© 2022
Inbound vs. outbound: Balancing your company’s sales strategies
It might sound like the lingo of air traffic controllers — inbound vs. outbound. But businesses of all types must grapple with these concepts and their associated challenges when developing sales strategies.
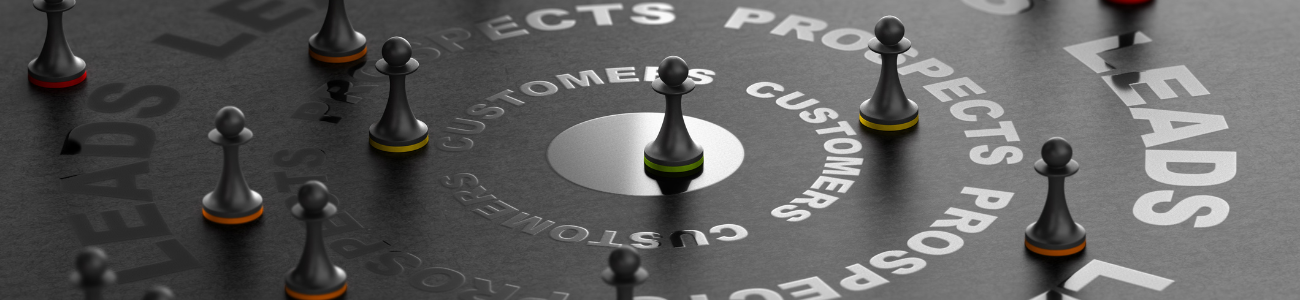
Inbound sales originate when someone contacts your company to inquire about buying a product or service, whereas outbound sales arise from members of your sales team reaching out to customers and prospects.
Like many businesses, yours may not have the luxury of choosing one approach over the other. You probably have to find the right balance.
Inbound sales: Marketing your brand
Inbound sales are all about marketing your brand. Customers and prospects need to know who you are and what you offer, otherwise they won’t be in touch.
Thus, you’ll need to invest in a strong brand-based, content-driven marketing strategy that establishes and maintains your reputation as a “destination business” in your industry. Interested parties who encounter your marketing materials should wind up thinking, “I want to go there.”
If you can accomplish that, you’ll need a well-trained, patient inside sales team who are experts on your products or services. The word “patient” is key. One of the downsides to inbound sales is that they can take longer to close than outbound sales. They’re also less targeted. You have to deal with whoever contacts you. Some prospects might show up with unrealistic expectations or turn out to be difficult customers.
On the plus side, inbound sales are typically less labor-intensive and expensive because the buyer is coming to you and your customer base is generally more concentrated. What’s more, inside sales teams may incur less turnover because of lower rejection rates and a greater emphasis on technical know-how over a traditional “make your numbers or else” mindset.
Outbound sales: Lots of work, big potential
Outbound sales are largely based on intensive market research. You need to know the demographics and other key data points of those most likely to buy from you — and then you’ve got to go out and get ’em.
The downside to outbound sales is they tend to entail much more work (cold calls, follow-up, virtual and/or in-person meetings) and typically incur a higher rejection rate. In addition, this approach is often more expensive. You’ll need to cast a much wider net in terms of marketing and advertising. Outside salespeople tend to work longer hours, and they may incur substantial travel expenses and have a higher turnover rate. You might need more of them to cover your sales territories, too.
All that said, under the right circumstances and when properly executed, outbound sales can generate more revenue than inbound sales. You can target a large number of precisely the types of customers who will most likely buy from you, and sales are often quicker and easier to close.
Assess your position
Has your company been running on autopilot when it comes to balancing inbound vs. outbound sales? Now’s a good time to address the issue as we head into the new year.
If, for example, you’re waiting around for inbound sales that aren’t showing up, maybe it’s time to pivot to an outbound sales strategy. On the other hand, if you’ve emerged as a major player in your market, perhaps you can cut back on the outreach, beef up your brand and rely more on inbound sales. Contact us for help evaluating your sales numbers, as well as identifying the costs and forecasting the potential revenue of both approaches.
© 2022

In your own words: A letter of instruction complements a will
A smart estate plan should leave no doubt as to your intentions. Writing a letter of instruction can go a long way toward clearly communicating all of your thoughts and wishes. Even though the letter, unlike a valid will, isn’t legally binding, it can be valuable to your surviving family members.
The devil is in the details
Although the content can vary from person to person, one of the main purposes of a letter of instruction is to provide details on final wishes that haven’t been conveyed in the will. Think of the letter as a way to fill in some of the “gaps” or resolve matters that may be left open to interpretation.
For example, your letter can detail vital financial information that was omitted or glossed over in your will. Typically, this can include an inventory of real estate holdings, investment accounts, bank accounts, retirement plan accounts and IRAs, life insurance policies, and other financial assets.
Along with the account numbers, list the locations of the documents, such as a safe deposit box or file cabinet. And don’t forget to provide the contact information for your estate planning team. Typically, this will include your attorney, CPA, investment advisor and life insurance agent. These professionals can assist your family during the aftermath.
Many people also use a letter to lay out their wishes for personal possessions. Keep in mind that without spelling out your intentions, bitter disputes may erupt over items that have more sentimental value than monetary worth, including furniture, photographs, jewelry and artwork.
Content is up to you
There are no hard-and-fast rules for writing a letter of instruction. The basic elements are outlined above, but the choices are ultimately up to you. Remember that the letter isn’t legally binding, so there is no obligation to include any particular item. Conversely, you can say pretty much whatever else you want to say.
Rewrite if necessary
Completing your letter of instruction shouldn’t be the end of the story. You may have to revisit it for rewrites or edits you didn’t accommodate before. For example, you may have neglected to specify certain accomplishments you want to be mentioned in an obituary.
In addition, it’s likely that some of your personal information will change over time, such as bank account numbers and passwords. Update the letter when warranted. Think of it as an ongoing process.
Finally, make sure that the letter is secured in a safe place. Any printed version should accompany your will or be located somewhere else that’s accessible to trusted family members. At the same time, you must be able to update the letter whenever you need to.
Clarity counts
If you haven’t done so already, draft a letter of instruction and, most important, make sure that your family knows where to locate it. We can help fill in the blanks if you need help.
© 2022
Timing is everything when it comes to accounting software upgrades
“Well, it still works, and everyone knows how to use it, but….”
Do these words sound familiar? Many businesses stick with their accounting software far too long for these very reasons. What’s important to find out and consider is everything that comes after the word “but.”
Managers and employees often struggle with systems that don’t provide all the functionality they need, such as being able to generate certain types of reports that could help the company better analyze its financials. Older software might constantly freeze up or crash. In some cases, the product may even be so old that support is no longer provided.
When it comes to accounting software upgrades, timing is everything. You don’t want to spend money unnecessarily if your system is fully functional and secure. But you also don’t want to wait too long and risk losing a competitive edge, suffering data loss or corruption, or incurring a security breach.
Building a knowledge base
The first question to ask yourself is: When was the last time we meaningfully upgraded our accounting software?
Many more products may have hit the market since you bought yours — including some that were developed specifically for your industry. Although most accounting software has the same essential features, it’s these specialized functions that hold the most potential value for certain types of companies.
To make an educated choice, business owners and their leadership teams need to gain a detailed understanding of their specific needs and the technological savvy of their employees. You can go about this knowledge-building effort in various ways, including conducting a user survey and putting together a comprehensive, detailed comparison of three or four accounting software products that appear best suited to your business.
If it appears highly likely that a new accounting system would markedly improve your financial tracking and reporting, you’ll be able to make a confident and well-advised purchasing decision.
Preparing for the transition
Bear in mind that buying the software will be the easy part. Transitioning to the new system will probably be much more challenging. When changing or significantly upgrading their accounting software, companies have to walk a fine line between:
Rushing the timeline, potentially mishandling setup issues and not providing sufficient training, and
Dragging their feet, potentially falling behind on financial reporting.
You might need to engage an IT consultant to help oversee the data transfer from the old system to the new, catch and clean up errors, and ensure strong cybersecurity measures are in place.
It’s a big decision
Moving onward and upward from a long-used accounting system is a big decision. Let us help you determine what software features would be most beneficial to your business, identify which current products would best fulfill your needs, and develop a sensible budget for the purchase.
© 2022

What’s the difference between a springing and a nonspringing power of attorney?
Estate planning typically focuses on what happens to your children and your assets when you die. But it’s equally important (some might say even more important) to have a plan for making critical financial and medical decisions if you’re unable to make those decisions yourself.
A crucial component of this plan is the power of attorney (POA). A POA appoints a trusted representative to make medical or financial decisions on your behalf in the event an accident or illness renders you unconscious or mentally incapacitated. Without it, your loved ones would have to petition a court for guardianship or conservatorship, a costly process that can delay urgent decisions.
A question that people often struggle with is whether a POA should be springing, that is, effective when certain conditions are met or nonspringing, that is, effective immediately.
A POA defined
A POA is a document under which you, as “principal,” authorize a representative to be your “agent” or “attorney-in-fact,” to act on your behalf. Typically, separate POAs are executed for health care and property.
A POA for health care authorizes your agent — often, a spouse, an adult child or other family member — to make medical decisions on your behalf or consent to or discontinue medical treatment if you’re unable to do so. Depending on the state you live in, the document may also be known as a medical power of attorney or health care proxy.
A POA for property appoints an agent to manage your investments, pay your bills, file tax returns, continue making any annual charitable and family gifts, and otherwise handle your finances, subject to limitations you establish.
To spring or not to spring
Typically, springing powers take effect when the principal becomes mentally incapacitated, comatose, or otherwise unable to act for himself or herself.
Nonspringing POAs offer a few advantages over springing POAs:
Because they’re effective immediately, nonspringing POAs allow your agent to act on your behalf for your convenience, not just when you’re incapacitated.
They avoid the need for a determination that you’ve become incapacitated, which can result in delays, disputes or even litigation. This allows your agent to act quickly in an emergency, making critical medical decisions or handling urgent financial matters without having to wait, for example, for one or more treating physicians to examine you and certify that you’re incapacitated.
A potential disadvantage to a nonspringing POA — and the main reason some people opt for a springing POA — is the concern that your agent may be tempted to abuse his or her authority or commit fraud. But consider this: If you don’t trust your agent enough to give him or her a POA that takes effect immediately, how does delaying its effect until you’re deemed incapacitated solve the problem?
Given the advantages of a nonspringing POA, and the potential delays associated with a springing POA, it’s usually preferable to use a nonspringing POA and to make sure the person you name as agent is someone you trust unconditionally. If you’re still uncomfortable handing over a POA that takes effect immediately, consider signing a nonspringing POA but have your attorney or other trusted advisor hold it and deliver it to your agent when needed.
Contact us if you have additional questions regarding a springing or nonspringing POA.
© 2022